Explore the Full Spectrum of Leadership and Life Mastery
Issue #156 Why the Most Expensive Word in Business Might be Yes
Brad Pedersn
November 13, 2026
•
10 min read


During the first ten years of building my first toy enterprise, we doubled the business every year.
It was an extraordinary period of growth, taking us from a bootstrapped startup to one of the largest toy distribution companies in Canada. And because this was my first experience building a business, I had little perspective on just how unusual our trajectory was.
All I really knew was growth.
We’d figured out how to identify opportunities, build relationships and scale a distribution business through innovative sales and marketing. And with each passing year, my confidence grew that we could apply the same formula elsewhere.
After all, if we’d been able to build something this successful in the toy industry, what was stopping us from doing it again in another industry?
As it turned out, an opportunity was about to present itself in a place I never would have expected.
An Opportunity Too Good to Ignore
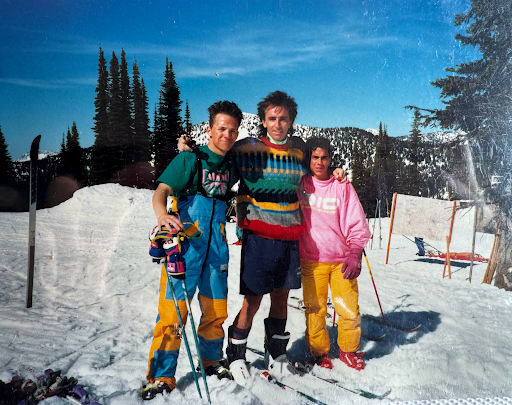
Through one of our distribution agreements, we became the distributor for Morey bodyboards in Canada. It was a modest business, with limited demand outside a few coastal markets and recreational operations. But it personally intrigued me because I’ve always been drawn to action sports, adventure and outdoor pursuits.
When we attended an industry trade event to meet our customers who were buying Morey products, I hadn’t anticipated how much the experience would expand my thinking. We went to support one of the smallest categories in our portfolio and found ourselves surrounded by an industry of brands that I loved.
As we explored the show and spoke with brand owners, we began wondering why we couldn’t apply our successful toy distribution model to this industry. We already had a foothold through Morey, and our track record in growing our toy business gave us confidence that we could scale another business.
We decided to pursue the opportunity, securing distribution relationships with several established brands in surf, wake and motocross. Within a relatively short time, we’d assembled a meaningful portfolio and launched a separate company called Outer Edge Industries.
It seemed like a logical decision. We believed we were diversifying our interests, strengthening our distribution position and creating another platform for growth. Having more than one business felt like a smart way to spread our risk.
What we failed to appreciate was just how different the industries were. Action sports had different customers, sales agents, buying cycles and operating requirements. Much of what we’d learned in toys didn’t translate as well as we’d assumed. And although we’d assembled a team to run Outer Edge, it still demanded leadership, capital and attention.
All of which had to come from somewhere.
The Cost of Distraction
At the time, what I couldn’t see clearly was that the resources we invested into Outer Edge were resources that we weren’t investing into our core business. We believed we were strengthening our position through diversification, but in fact we were stretching ourselves thin across two very different enterprises.
Only a few years after launching Outer Edge, our toy business reached a critical inflection point. We’d grown too quickly without the profit structure necessary to support that growth, and the financial pressures forced us into special loans and eventually a restructuring.
Several factors contributed to those difficulties, and Outer Edge wasn’t solely responsible. But dividing our focus undoubtedly contributed to the foundational cracks within our core business.
The restructuring forced us to sell off Outer Edge’s assets, ending the venture we’d created with the vision of strengthening our position. And despite these desperate measures, the financial difficulties we faced at the time were too great and we would eventually end up bankrupting the core enterprise.
There’s an irony in that outcome that isn’t lost on me. We pursued a second business believing it would make us more financially resilient. Instead, by stretching our leadership and resources too thin, we compromised our ability to execute effectively in either one.
What we thought was diversification had actually become a distraction.
And I’ve come to recognize that the problem went deeper than just a poor strategic decision.
The Success Bubble
Success has a way of creating its own blind spots. When things go well over an extended period of time, confidence can actually degrade into hubris.
I’d spent a decade building and scaling a business from nothing into a significant eight figure enterprise and had become accustomed to finding ways to fund and sustain its growth. However I had underestimated how uncommon the results were and I had overestimated how readily that success could be repeated.
Compounding the problem, I’d surrounded myself with team members who weren’t particularly inclined to challenge me. As a first-time entrepreneur, I hadn’t developed the maturity to recognize the importance of hiring people who were better than me at their respective roles. Instead, I tended to hire people I felt comfortable leading, people who didn’t intimidate me.
There’s a phenomenon in organizational psychology known as the MUM effect, describing our reluctance to communicate unpleasant messages especially when things seem to be good and growing. When this happens, the people in the organization start to hesitate to question a leader whose judgment has consistently been rewarded by results.
It’s also what is known as a success bubble.
But what is required in a growing enterprise are truth tellers. And the more successful we become, the more important it is to have truth-tellers around us. Healthy organizations need the candour that allows for what Patrick Lencioni describes as constructive conflict, where people challenge assumptions because they’re committed to achieving a better outcome.
It’s not about trying to be right, but about having the courage to help everyone get it right.
Reflecting on the leadership team I had assembled at the time, I hadn’t created enough room for those around me to challenge my thinking. My confidence in the opportunity exceeded my appreciation for the risks, and I didn’t have the right people around me to question my assumptions.
From Discovery to Discipline
One of the things I’ve learned is that entrepreneurship requires two different mindsets at different stages of the journey.
In the beginning, we need to say yes. We experiment, explore opportunities, test ideas and make mistakes. We don’t yet know where we’ll find traction, so curiosity and a willingness to try different things are essential.
Eventually, if we’re fortunate, we discover something that connects. We find ourselves at the intersection of what we love doing, what we’re genuinely good at and what can drive a sustainable economic engine.
But once we’ve discovered that intersection, the rules need to change.
The willingness to pursue opportunities that helped us discover our business can become a liability if we continue operating that way after finding our focus. The challenge shifts from exploring possibilities to developing the discipline to say no to attractive opportunities that compete for our attention.
Jim Collins captured this distinction with a phrase I’ve come to appreciate: Good is the enemy of great. The idea that there are countless good opportunities we could pursue, but relatively few things we have the potential to become truly great at.
Building a world-class enterprise requires sustained attention, continuous improvement and vigilance. Business is difficult enough when we’re focused. Competition is relentless, margins can be thin and profits can evaporate quickly when we lose our discipline.
Looking back, we’d already found something special in our toy enterprise. We’d developed relationships, capabilities and market knowledge that allowed us to grow at an extraordinary pace. But rather than strengthening the financial and operational foundation needed to sustain that growth, we became distracted by trying to build something new.
My passion for action sports blurred my view on if it was a good opportunity or the right one. I have since learned that being passionate about an industry and having a sound business model within that industry are two very different things.
Keeping the Main Thing the Main Thing
Jim Collins offers another principle I’ve come to appreciate: preserve the core and stimulate progress.
I interpret that as keeping the main thing the main thing, while continually finding ways to improve, innovate and grow around it. This isn’t an argument against new opportunities or calculated risks. Progress is essential, but there’s a difference between strengthening an enterprise and distracting it with an entirely different business model.
In retrospect, we should have concentrated on improving our toy company’s financial structure, deepening relationships with partners and developing the systems necessary for sustainable growth. Instead, we entered an unfamiliar industry before we’d fully established the foundation our core business needed.
That was premature, and it reflected poor judgment influenced by my confidence and enthusiasm. This was further compounded by the fact that I had no one around me willing to challenge my thinking. I believed having two businesses gave us two opportunities to succeed, without appreciating that they were competing for the same finite resources.
I thought I was diversifying our opportunities. In reality, I was diluting our effectiveness.
It’s a distinction I understand much better today.
The Wisdom to Say No
If you are a business leader of a growing enterprise, you will be constantly enticed by new opportunities that look exciting and shiny. However, I’ve come to believe that these opportunities are often distractions in disguise. They arrive promising additional growth, excitement or additional revenue, making it easy to underestimate the attention and resources they’ll demand.
The difficult decisions rarely involve choosing between something obviously good and something bad. More often, we’re choosing among worthwhile possibilities, knowing we can’t pursue them all equally well.
As a younger entrepreneur, I was better at identifying possibilities than evaluating their true cost. I’ve since learned that saying no to an attractive opportunity isn’t a sign of low ambition; instead it’s the discipline required to protect something that is more important.
This extends beyond business. Our lives are filled with worthwhile commitments and requests for our time. Yet when we say yes to too many, we risk spreading ourselves so thin that we give insufficient attention to what matters most.
There’s a difference between being busy with good things and being effective at the things that deserve our best.
And that’s one of the more difficult lessons that comes with experience. In the early stages of entrepreneurship, saying yes helps us discover what’s possible. But once we’ve found our focus, learning to say no is what gives us the opportunity to truly become great.
I’ve come to realize that the greatest opportunity isn’t always the next one waiting to be discovered. Sometimes it’s the one we’ve already found, and having the wisdom to protect it from the many good opportunities that threaten to distract us.
One Question
It’s worth occasionally taking inventory of the opportunities and commitments competing for our attention. Not because they lack merit, but because even worthwhile pursuits come at a cost.
Sometimes the hardest thing to recognize is that what we’re saying yes to may be preventing us from giving our best to something that matters more.
So with that in mind, the question I would challenge you to consider is:
What’s one good opportunity you’re pursuing today that might be preventing you from becoming great at something more important?
New here?
Discover Where You're Thriving and Ready to Grow

Subscribe to Full Spectrum Newsletter
Get insights delivered to your inbox monthly.
Subscribe to Full Spectrum Newsletter
Get insights delivered to your inbox monthly.
